A credit card balance can seem harmless when it first appears. Maybe you covered a car repair, a medical bill, or a few weeks of groceries after an unexpected expense. The monthly payment feels manageable, so you tell yourself you will pay it off later. For many middle-class households, however, that later never arrives. The balance stays, the interest adds up, and the card becomes a source of quiet, constant financial stress.
The first consequence is the monthly squeeze. When a large portion of your paycheck goes toward minimum payments, there is less room for everything else. Saving for retirement slows. Vacation plans disappear. You might delay replacing worn tires or taking a child to the dentist because the money is already spoken for. The stress is not just about one bill. It is about the feeling that your income is working for old purchases instead of your current life.
Minimum payments make this problem worse because they are designed to keep the account open, not to pay it off quickly. A small minimum payment can create a false sense of progress. You send money every month, yet the balance barely moves. Interest charges eat a large share of what you pay. Over time, you may pay hundreds or thousands of dollars extra for things you bought years ago. That realization can be frustrating and demoralizing.
Financial stress also drains your emergency cushion. When you are already carrying debt, building savings feels impossible. So when the next unexpected expense arrives, the credit card becomes the emergency fund. This creates a loop. The balance grows, the payment grows, and your ability to save shrinks. A flat tire or a broken refrigerator can undo months of careful budgeting. The stress becomes less about one bad month and more about never feeling secure.
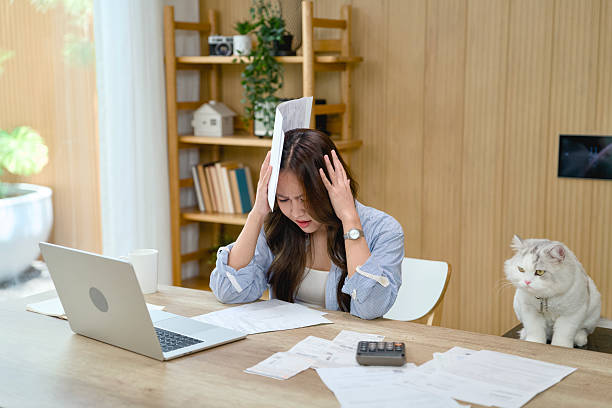
The emotional weight is just as real. Financial stress follows you into the grocery store, where you second-guess every purchase. It shows up at night when you lie awake doing math in your head. It can strain relationships because money conversations become tense. Partners may argue about spending, secrecy, or whose fault the debt is. Even when the balance is not discussed, it sits in the background, shaping decisions about holidays, meals, and whether you can say yes to a night out with friends.
There are practical consequences too. Using a large share of your available credit can lower your credit score. A lower score can lead to higher interest rates on future loans, which makes cars and homes more expensive. It can also make it harder to rent an apartment or qualify for certain jobs that check credit. These outcomes are not abstract. They limit your choices and add another layer of worry.
Middle-class families often face a particular kind of pressure. They may earn too much to qualify for many forms of assistance, but not enough to absorb a major setback without borrowing. Housing costs, childcare, insurance, and groceries have risen. Credit cards can feel like the only way to bridge the gap. Once that bridge becomes permanent, the stress becomes permanent too.
The way out usually starts with awareness. Adding up all balances and writing down the interest rates can be uncomfortable, but it replaces vague fear with facts. From there, stopping new charges is critical. It is hard to pay down a balance while adding to it. Paying more than the minimum, even a little, can make a difference over time. A small emergency fund, even a few hundred dollars, can reduce reliance on credit when something goes wrong. Talking openly with a partner or family member can also lighten the emotional load.
For some people, a nonprofit credit counselor or a debt payoff plan can provide structure and relief. The goal is not to shame anyone for using credit. Credit is a tool, and sometimes it is the only tool available. But when balances become long-term, the consequence is not just money owed. It is lost sleep, strained relationships, and a constant feeling of being behind. Paying down debt is not only a financial project. It is a way to reclaim peace of mind.