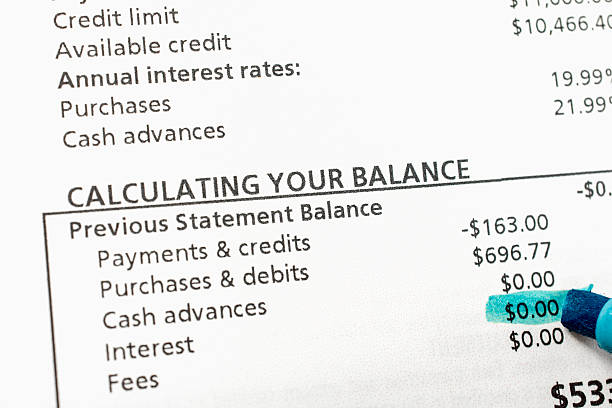
A chargeoff sounds like the end of the road. It is not. When you stop paying a credit card, personal loan, or other account, the lender eventually gives up on collecting the debt for its own books. That move is called a chargeoff. It usually happens after about six months of missed payments. But a chargeoff does not erase what you owe. The lender can still ask you to pay, or it can sell the debt to a collection agency. For a middle-class household, a chargeoff can create problems that last for years.
The first consequence is damage to your credit score. Payment history is the biggest factor in most credit scores, and a chargeoff is one of the most serious negative marks you can have. Your score may drop by a large amount, especially if you already had high balances or other late payments. The chargeoff can stay on your credit report for seven years from the date you first fell behind. As time passes, its impact may fade, but it does not simply vanish. If the debt is sold, your report may show the original chargeoff and a separate collection account. That can make your credit look even riskier to lenders.
The second consequence is that new credit becomes harder to get, or more expensive. Credit card companies may deny you or approve you only for a high-fee, high-rate card with a small limit. Auto loans may come with higher rates, which can add hundreds of dollars to the cost of a car. A mortgage can be especially difficult. Many mortgage lenders want a charged-off account to be paid, settled, or placed on a payment plan before they will approve a loan. Even after you resolve it, you may need to wait and provide a larger down payment. Landlords may also check your credit. A chargeoff can lead to a larger security deposit, a co-signer requirement, or a denied rental application.
The debt itself does not disappear. A collection agency may call or send letters. If you ignore those messages, the collector may sue you. If the collector wins, the court can order your employer to withhold part of your paycheck or allow the collector to take money from your bank account. That can hurt a middle-class family living paycheck to paycheck. The time limit for a lawsuit varies by state, but a court judgment can follow you for years. It may also appear on your credit report and make it harder to borrow. Dealing with the debt before a lawsuit is usually less stressful and less expensive than waiting.
You do have options. You can contact the original creditor or the collection agency and ask about a settlement. In many cases, you can pay less than the full balance if you can offer a lump sum. If you cannot pay a lump sum, ask for a payment plan you can afford. If you negotiate, get the agreement in writing before you send money. Avoid giving a collector direct access to your bank account. Use a cashier’s check or money order instead. Keep copies of every letter and note every phone call. If a collector harasses you or lies to you, you can file a complaint with state or federal regulators.
After a chargeoff, rebuilding credit takes time. The negative mark stays for years, but you can add positive information. Bring any other accounts current. Pay every bill on time. Keep credit card balances low compared with your limits. A secured credit card or a credit-builder loan can help you establish new payment history. Check your credit reports for errors, and dispute anything that is wrong. Companies that promise to remove an accurate chargeoff for a fee cannot legally do so. What you can do is show lenders that the chargeoff is in your past.
A chargeoff is a consequence, not a permanent label. If you are falling behind, contact your lender before the account is charged off. If the chargeoff already happened, make a realistic plan to settle, pay, or negotiate. Then focus on steady, on-time payments and lower balances. Middle-class consumers often recover from chargeoffs with patience and a clear plan. The sooner you face the problem, the sooner you can move beyond it.