For most middle-class families, the monthly electricity bill, water charge, internet payment, and cell phone plan are just part of the background noise of daily life. They are expected, automatic, and easy to overlook. But when income dips—a job loss, a medical emergency, or even a costly car repair—these same bills can quickly transform from routine expenses into a quiet and stressful debt problem. Unlike credit card debt or a personal loan, utility and services debt does not get the same attention. There are no glossy mailers or credit score warnings. Instead, the pressure builds up slowly, often through late notices, shutoff threats, and mounting late fees. And for many people, this type of debt is more damaging than they realize, because it attacks the very necessities of everyday living.
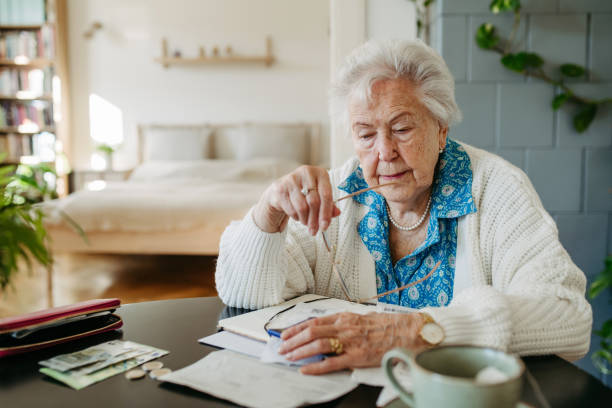
The first thing to understand is how utility debt typically begins. A middle-class household usually pays their electricity and gas on time. Then one month, cash flow is tight because an unexpected bill arrived. Perhaps the car needed new tires, or a child had a dental emergency. The decision becomes simple: pay the urgent expense now and put off the utility bill for a week or two. That delay usually works out. But if the tight cash flow continues into the next month, the utility bill from last month is still due, and the new one is arriving soon. Now the family owes double. Late fees get added. The provider may send a warning notice. This is the slippery slope. The debt itself is not huge, but it compounds because the service keeps being used every day. You cannot simply pause your electricity to catch up. Water keeps running, the internet stays on, and your family needs heat. So you fall further behind while still consuming the service.
A common and dangerous mistake is to prioritize other debts over utilities. Many consumers worry more about credit card minimum payments or auto loans because those appear on credit reports and feel more “official.” Utility companies, however, report to credit bureaus as well, especially when an account goes to collections. A single unpaid electric bill that is sent to a collection agency can drop a credit score by a significant amount. Worse, it stays on your credit report for seven years. For a middle-class consumer hoping to refinance a mortgage or buy a new car, that one utility debt becomes a real obstacle. The irony is that the dollar amount might be only a few hundred dollars, but the damage to financial reputation is outsized.
What can a consumer do when utility debt becomes overwhelming? The first step is to stop avoiding the provider. Many people feel shame or fear, so they ignore the notices until the shutoff notice arrives. But utility companies are actually some of the more flexible creditors when it comes to helping customers. They prefer to receive partial payments over time rather than spend money on shutting off service and later reconnecting it. Calling the customer service number and explaining the situation plainly is often the start of a resolution. Ask for a payment plan. Many providers will split the overdue amount across the next several monthly bills. Some offer an extension of the due date by a week or two. Others, especially in colder months, have state-regulated protections that prevent disconnection during extreme weather. It is worth asking directly for any assistance programs available for middle-income households. The idea that assistance is only for low-income families is no longer true. Many utility companies have emergency funds, discount rates, or community partnerships that can help a family that is temporarily overextended.
Another practical step is to audit the services themselves. Sometimes the debt is not just from a one-time crisis but from ongoing overspending on services. Most middle-class households pay for more than they actually use. Premium cable packages with channels nobody watches, unlimited data plans that barely hit their cap, or a landline that has not rung in months are all sources of unnecessary expense. Cutting one or two of these services can free up enough cash immediately to start catching up on the essential utilities. This is not about living without. It is about aligning spending with actual needs. A family can easily save fifty to a hundred dollars a month by trimming these extras. That money can go directly toward the overdue balance.
There is also the option of a temporary hardship accommodation. If you can document the reason for your financial stress—like a layoff notice, medical bill, or reduced work hours—some utility providers will reduce your current bill or waive late fees for a set period. The key is to ask before the account goes into default. Providers have much more discretion when the customer is proactive and honest. Once the debt is turned over to a collection agency, the utility company often loses the ability to negotiate. At that point, the consumer is dealing with a third-party collector who cares less about maintaining a relationship and more about collecting the full amount. So timing matters. Act early, not at the last minute.
Finally, it helps to think about utility and services debt as a warning sign rather than a personal failure. It often indicates that the monthly budget has become too tight. That can be a signal to look at the bigger picture of your finances—perhaps an emergency savings fund is too small, or monthly fixed costs are too high relative to income. The debt itself hurts, but the lesson is more valuable. Middle-class consumers can recover from a few hundred dollars of utility debt. The recovery becomes harder if the same pattern repeats every year. Using the experience to build a small buffer for future unexpected expenses is the best way to prevent a return visit. A stable home with lights on and water running is not a luxury. It is the foundation upon which all other financial efforts rest. When that foundation cracks, repairing it quickly and honestly is the only way forward.